Foreign-Owned U.S. LLC Compliance
- One pro forma Form 1120
- One Form 5472
- One related party included
Starting at $500
per LLC, per tax year
Forms included
Related party
Routine turnaround
IRS submission
Does this service fit your LLC?
This service is generally designed for an LLC that:
- Was formed under the law of a U.S. state;
- Has only one owner;
- Is wholly owned by a non-U.S. individual or foreign entity;
- Has not elected to be taxed as a corporation; and
- Had one or more reportable transactions with its foreign owner or another related party.
Please contact us before relying on the routine price if the LLC:
- Has or had more than one owner;
- Changed owners during the year;
- Made a corporate tax election;
- Has U.S. employees, dependent agents, or a U.S. office;
- Stores inventory with a U.S. fulfillment provider;
- Owns U.S. real estate;
- Received Forms 1099-K, 1042-S, or other U.S. tax forms;
- Was dissolved, revived, converted, or administratively closed;
- Has several unfiled years; or
- May be engaged in a U.S. trade or business.
No revenue, no profit, no U.S. bank account, or no owner withdrawals does not automatically eliminate the filing requirement. Formation costs, owner funding, registered-agent fees, loans, reimbursements, distributions, and expenses paid personally by the owner may be reportable transactions.
What forms are prepared?
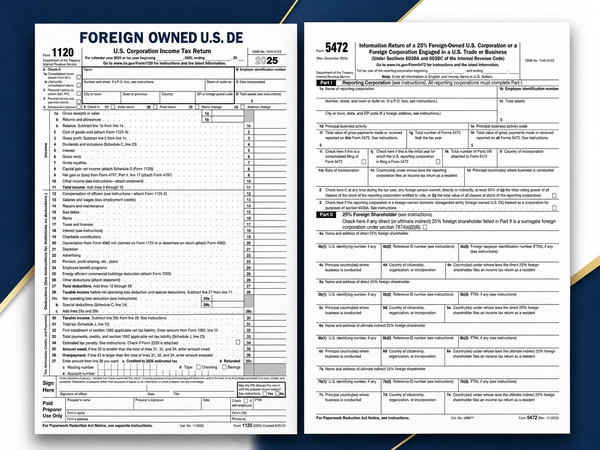
Pro forma Form 1120
A limited corporate-return cover page used to submit the foreign-owned disregarded entity's information return. It is not a complete C corporation income tax return.
Form 5472
The information return that reports ownership and qualifying transactions between the LLC and each reportable related party.
Routine, on-time filing
Routine, on-time filing
The routine package includes one pro forma Form 1120 and one Form 5472 for one related party, usually the foreign owner.
Additional related party
Additional related party
Add $100 for each additional related party requiring a separate Form 5472
The surcharge is based on the number of additional related parties that must be separately reported. It is not based on the number of transfers involving the same related party.
Late-filing options
Filing without an attached reasonable-cause statement
Starting at $500 per LLC, per year
Preparation of an otherwise routine delinquent Form 5472 and pro forma Form 1120 package. This does not include penalty defense.
Filing with a protective reasonable-cause statement
$1,500 per LLC, per year
The $500 filing package plus $1,000 for factual review, statement drafting, professional review, finalization, and submission with the delinquent package.
Response to an IRS Form 5472 penalty notice
$3,000 per penalty year
A separate post-notice penalty-defense engagement. Multiple penalty years are billed separately.
Tax consultations
15 minutes
$175
30 minutes
$225
60 minutes
$325
After-hours or weekend, 30 minutes
$500
The final engagement letter controls the scope and fee. Prices are reviewed periodically.
2025 calendar-year filing
The filing is generally due April 15 following the close of the calendar year. A timely Form 7004 generally extends the deadline for six months to October 15. If a due date falls on a weekend or legal holiday, the next-business-day rule may apply.
Form 7004 must be filed by the original due date. A late Form 7004 does not retroactively extend a filing that is already delinquent.
April 15, 2026
Calendar-year filing
October 15, 2026
If a valid Form 7004 was filed by April 15, 2026
2025 calendar-year deadlines: Original deadline: April 15, 2026 | Extended deadline: October 15, 2026, if a valid Form 7004 was filed by April 15, 2026.
ALREADY LATE?
File promptly and choose the filing strategy deliberately. A $25,000 Form 5472 penalty may apply when a required return is not timely and properly filed. Review our detailed late-filing FAQ or request a late-filing quote.
What the routine package includes
What the routine package includes
- Preparation of one pro forma Form 1120;
- Preparation of one Form 5472 for one related party;
- Review of the completed Form 5472 organizer and supporting documents;
- Classification and reporting of related-party amounts identified in the organizer;
- Professional preparation and finalization of the filing package;
- A draft for the client's factual review;
- Revision of confirmed factual errors before filing;
- Signature and filing instructions;
- Fax submission when included or requested in the engagement; and
- A final filing package and available transmission confirmation for the client's records.
What is not included in the routine package
- Bookkeeping or reconstruction from bank statements, Stripe reports, Amazon settlement reports, PayPal records, receipts, or raw accounting data;
- Stand-alone review, certification, or correction of forms prepared by the client or another firm;
- Determining whether the foreign owner is engaged in a U.S. trade or business or has effectively connected income;
- Form 1040-NR preparation or a definitive determination that Form 1040-NR is or is not required;
- ITIN eligibility analysis or Form W-7 preparation;
- Treaty, permanent-establishment, income-sourcing, withholding, W-8, W-9, Form 1099, Form 1042, payroll, or sales-tax analysis;
- State income tax, franchise tax, annual reports, registered-agent fees, or state dissolution filings;
- Entity formation, conversion, ownership transfers, EIN applications, or EIN closure;
- Amended returns, protective income-tax returns, tax elections, or unrelated federal forms;
- A reasonable-cause statement unless the $1,500 late-filing package is selected; or
- IRS notice responses, penalty abatement, audit defense, appeals, or other representation after filing.
If additional work is needed, we identify the appropriate consultation or separate engagement before beginning that work.
How the engagement works
Initial scope check
Tell us the LLC's formation state and date, ownership, tax year or years, filing status, number of related parties, business activity, and whether the filing is on time or late.
If the matter is clearly routine, we can usually confirm the published fee and next steps. A complimentary 10-minute call may be used for a narrow fit, scope, or organizer question. It is not a substitute for personalized tax advice.
Secure client portal
If we move forward, we send an invitation to TaxDome, our secure portal for documents, messages, engagement materials, and invoices.
Organizer and supporting records
The client completes our Form 5472 organizer and reviews the FAQ tab and instructional walkthrough. The organizer converts the client's records into the information required for preparation.
We prepare the filing from the completed organizer and supporting documents. We do not prepare the routine filing from unorganized raw transaction data.
Final scope, engagement letter, and invoice
After receiving a usable organizer and required documents, we confirm the filing years, related parties, and any additional work. We then issue the engagement letter and invoice.
Payment is required before preparation begins. Card payments may be made through TaxDome or stripe link.
Preparation
A complete, routine file is generally drafted within 3-5 business days after all required information and payment are received.
Multi-year, late, amended, unusually complex, incomplete, or peak-season files may require 7-14 business days or longer. Turnaround begins when the file is complete and ready for preparation.
Draft review
We send the draft for review. The client must carefully verify:
- LLC legal name, address, and EIN;
- Tax year and initial or final return status;
- Foreign owner and related-party details;
- Foreign taxpayer identification number, if any;
- Principal business activity and NAICS code; and
- Reportable transaction descriptions and annual amounts.
Signature and IRS submission
After approval, the client signs the required filing pages. A foreign-owned U.S. disregarded entity cannot e-file this Form 5472 package. The IRS currently requires fax or mail submission through its special filing procedure.
Completion package
After transmission, we provide the final filing package and available fax confirmation. A transmission confirmation is evidence of submission.
Documents and information we usually need
Please be prepared to provide:
-
01
A completed Form 5472 organizer for each tax year;
-
02
LLC formation documents;
-
03
The IRS EIN confirmation letter;
-
04
The operating agreement, if any;
-
05
Prior federal filings for the LLC, if any;
-
06
The foreign owner's complete legal name, residential address, country of residence or organization, and foreign taxpayer identification number, if any;
-
07
The LLC's business description and preferred NAICS code, if known;
-
08
The identity of every related person or entity that had a reportable transaction with the LLC;
-
09
Annual totals for owner contributions, distributions, loans, reimbursements, owner-paid LLC expenses, formation costs, and other reportable transactions;
-
10
Clarification of which bank or payment account received business income and which account paid expenses;
-
11
Details of ownership changes, dissolution, revival, conversion, or tax elections; and
-
12
Relevant IRS notices and information returns, including Forms 1099-K or 1042-S, if received.
What we can answer by email and what requires a consultation
We can generally address by email
- Whether the described facts appear to fit this service
- Published pricing and the related-party surcharge
- The standard document list
- Portal, payment, signature, and filing logistics
- Current turnaround expectations
- Narrow organizer clarification after review of the instructions
A paid consultation may include a written summary of the main issues discussed. A formal signed tax or legal memorandum is separately scoped and quoted.
A paid consultation is required for
- U.S. trade or business or effectively connected income
- Whether Form 1040-NR is required
- ITIN eligibility or whether an ITIN is needed
- Income sourcing, treaty benefits, or permanent-establishment risk
- U.S. employees, agents, contractors, offices, travel, inventory, or 3PL arrangements
- Amazon FBA, Shopify, Stripe, PayPal, marketplace, or payment-processor tax consequences
- State income tax, franchise tax, sales tax, payroll, or nexus
- Characterizing a payment as a contribution, loan, reimbursement, or distribution
- Choosing a late-filing or reasonable-cause strategy
- Penalty-defense strength, restructuring, ownership changes, or dissolution strategy
We advise only on the U.S. side unless the engagement states otherwise. Tax treatment in the owner's home country should be addressed with a qualified adviser in that country.
Industries and business models we frequently see
E-commerce and marketplaces, including Amazon FBA, Shopify, eBay, Etsy, dropshipping, and U.S. 3PL fulfillment;
SaaS, software development, apps, artificial intelligence, cybersecurity, and digital platforms;
Remote consulting, coaching, professional services, contractors, and B2B service businesses;
Digital marketing, advertising, lead generation, and online agencies;
Media, online courses, digital products, content, and royalty-based businesses;
Import-export and physical-product businesses; and
Holding, investment, fintech, and real-estate-related structures requiring additional fact review.
Frequently asked questions
Filing requirements and forms
For this limited reporting rule, a wholly foreign-owned U.S. disregarded entity files a partially completed Form 1120 as the cover return and attaches Form 5472. It does not by itself mean the LLC elected to become a C corporation.
No. Form 5472 is an information return. Whether the foreign owner has U.S. taxable income, a U.S. trade or business, effectively connected income, withholding, or a Form 1040-NR obligation is a separate analysis.
No revenue does not automatically mean no filing. Formation costs, registered-agent fees, state fees, capital contributions, owner-paid expenses, loans, reimbursements, and distributions can be reportable related-party transactions.
That fact alone does not decide the filing requirement. Payments made personally by the owner or through a foreign account can still be transactions between the owner and the LLC.
Often, yes. A newly formed LLC is normally funded in some manner, and someone pays the formation or initial operating costs. The answer depends on the actual transactions, not merely whether the business generated sales.
Not necessarily. The LLC generally needs an EIN. Form 5472 requests the foreign owner's foreign taxpayer identification number, if any. The absence of an ITIN does not by itself prevent preparation. Whether the owner separately needs an ITIN or Form 1040-NR is a different question.
No single fact answers that question. The analysis can depend on where services are performed, inventory and fulfillment, personnel and agents, contracts, travel, sourcing rules, and other facts. We address this through a paid consultation, not a categorical email answer.
Pricing and preparation
Yes. The current base fee is $500 per LLC, per tax year for an otherwise routine filing with one related party, typically the foreign owner.
No. It applies to each additional related party requiring a separate Form 5472, not to every wire, contribution, distribution, or recurring transfer involving the same related party.
Multiple transfers involving the same foreign owner do not automatically increase the fee. We report annual amounts and required transaction categories based on the organizer. Additional related parties or unusual complexity can change the scope.
Not as part of the $500 package. The client must provide organized annual totals through our organizer. Bookkeeping or transaction reconstruction is separately scoped and priced.
No. We do not offer a stand-alone review or certification service for third-party or self-prepared Forms 5472 and pro forma Forms 1120. We prepare the engagement from the beginning using our organizer and process.
Routine, complete files are generally drafted within 3-5 business days after all required information and payment are received. Multi-year, late, complex, incomplete, or peak-season files may require 7-14 business days.
No. The standard fee applies per filing whether the client comes directly or through a partner. A white-label or back-office relationship may be arranged, but each file is billed at the standard rate when submitted and payment is required before work begins.
Deadlines, filing, and penalties
For a calendar-year LLC, the regular due date is generally April 15. A timely Form 7004 generally extends the deadline to October 15. A valid extension must be filed by the original due date.
No. Once the original due date passes without a timely extension, the filing is late. Filing promptly may still be important, but the strategy and penalty risk must be addressed separately.
No. The IRS currently states that a foreign-owned U.S. disregarded entity cannot electronically file this Form 5472 package. It must be faxed or mailed to the dedicated IRS destination.
Yes, when fax submission is included or requested under the engagement. We provide the available transmission confirmation. The client may also file by fax or mail if that is the agreed procedure.
For an otherwise routine delinquent filing, the two common approaches are filing without an attached reasonable-cause statement, starting at $500 per year, or filing with a protective reasonable-cause statement for $1,500 per year. The proper approach depends on the facts.
No. The IRS may process a late return without a penalty, or it may issue a penalty notice even when a statement is attached. No preparer can guarantee penalty relief.
The IRS instructions state that failure to file a complete Form 5472 on time and in the required manner can trigger a $25,000 penalty. Additional penalties may apply if the failure continues after IRS notice.
No. A protective statement filed with a delinquent return and a later IRS penalty-defense engagement are different services. The current fee for Form 5472 penalty defense is $3,000 per penalty year unless a different written quote applies.
Each reportable tax year requires a separate filing. We first identify which years had reportable transactions. A dormant year is not automatically excluded if there was owner funding, fees, expenses, loans, or other related-party activity.
Entity, state, and advisory questions
A dissolved or cancelled LLC may still need a final federal filing for the relevant period. State dissolution, franchise taxes, annual reports, and EIN closure are separate services.
Revival can create a multi-year scope question. We usually need a timeline, state records, prior filings, bank and payment-processor history, and annual related-party activity before quoting the complete cleanup.
No. California Form 568, state franchise-tax returns, annual reports, sales-tax filings, and other state obligations are separate. The federal Form 5472 package does not resolve state compliance.
No. We advise on U.S. federal and, when separately engaged, U.S. state issues. A qualified adviser in the owner's country should address local tax, foreign-tax-credit, entity-characterization, and local permanent-establishment questions.
The free call is for a narrow scope, fit, or organizer clarification. A paid consultation is for personalized analysis and recommendations involving U.S. trade or business, ECI, Form 1040-NR, ITIN, sourcing, treaties, state nexus, sales tax, payroll, or structuring.
A consultation may include a written summary of the principal issues discussed. A formal signed tax or legal memorandum is a separate engagement and is quoted based on scope.
Provide the LLC's legal name, state and date of formation, tax year or years, owner type and country, number of related parties, main transaction categories, whether a timely extension was filed, whether the LLC was dissolved or revived, and whether there are U.S. employees, agents, offices, inventory, real estate, travel, or tax forms.
Routine filing package
Form 5472 and Pro Forma Form 1120
Choose the right next step
I know I need a routine Form 5472 package
Use the contact form and provide the quick-quote information listed above. We will confirm fit, send the organizer, and begin onboarding.
Request a routine filing quote ↗I am late and my facts are straightforward
Tell us the delinquent year or years and whether you want a quote for filing only or filing with a protective reasonable-cause statement.
Request a late-filing quote ↗I am unsure whether I must file or whether I owe U.S. tax
Book a paid consultation. This is the correct path for U.S. trade or business, ECI, Form 1040-NR, ITIN, treaty, sourcing, state nexus, sales tax, payroll, or structuring questions.
Book a tax consultation ↗Authoritative IRS references
